PROPERTY REFURBISHMENT
Finance for a property with work to do.
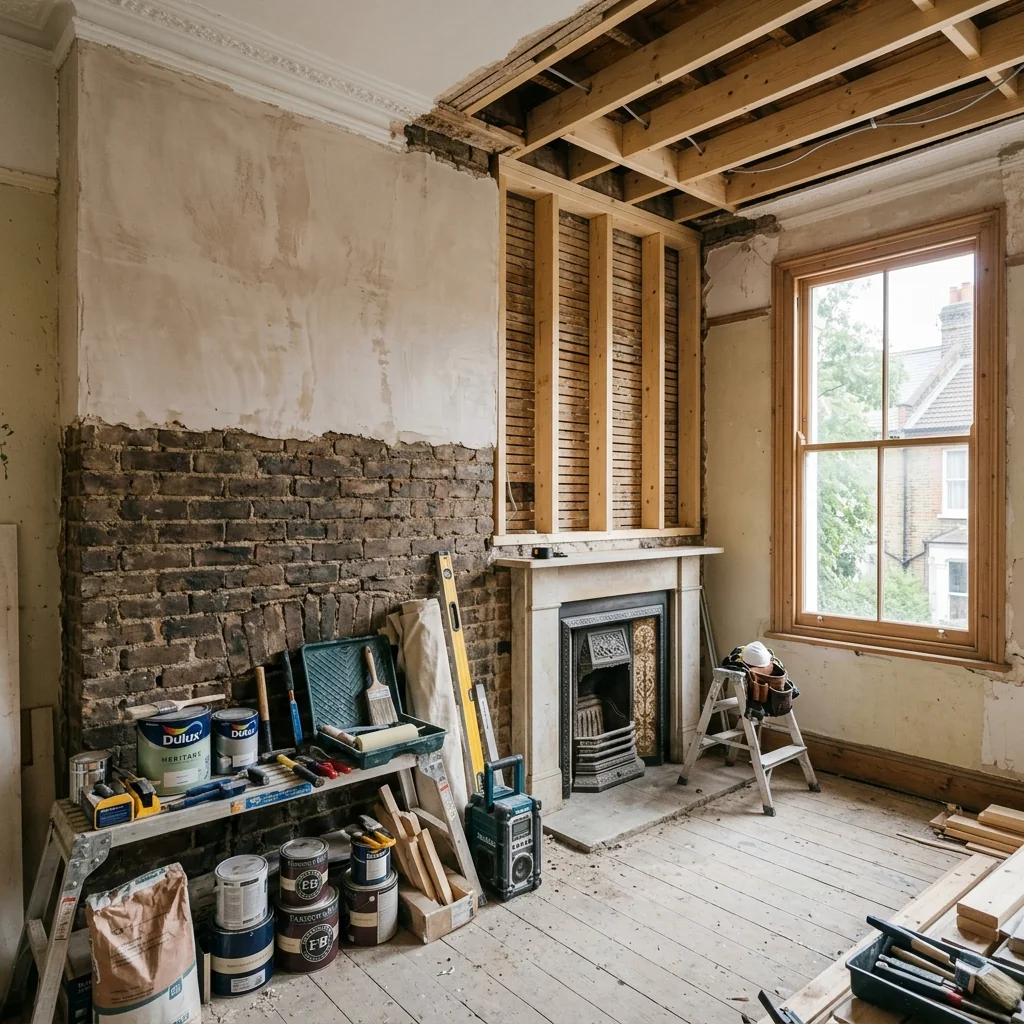
Finance for properties that need work before they can be let or sold. We arrange purchase plus works funding for both light cosmetic refurbishments and full structural renovations.
Mortgage advice, made simple
Get clear advice before you apply.
Tell us about the works, timescale and exit route.
- FCA regulated, whole-of-market mortgage advice.
- No jargon and no pressure to proceed.
- We explain fees, risks and next steps before any application.
Your home may be repossessed if you do not keep up repayments on your mortgage. Some specialist or buy-to-let finance may not be regulated by the FCA.
Light refurb vs heavy refurb
Light refurbishment
Cosmetic improvements that do not require planning permission or structural work. New kitchen, bathroom, redecoration, flooring, garden tidying. Generally completed within 6 months. Many bridging lenders offer specific light refurb products with competitive rates.
Heavy refurbishment
Structural changes such as extensions, loft conversions, reconfiguring layouts, underpinning, or full rewiring and replumbing. Often requires planning permission and building regulations sign-off. Funded through specialist refurb bridging with staged drawdowns.
How the finance works
A refurbishment bridge provides funding to purchase the property plus a separate works facility to cover the renovation costs. The purchase element completes on day one. The works element is drawn down in agreed stages, subject to the lender's progress checks.
Interest may be rolled up or paid monthly, depending on the facility. Plan to repay by the agreed date through a sale or refinancing, neither of which is guaranteed.
Common questions
Do I need planning permission?
How is the works facility released?
What if the project overruns?
Exit to buy-to-let
From wreck to rental in one facility
We structure refurbishment finance with your exit in mind from day one. Whether you plan to sell at a profit or hold as a rental, we make sure the numbers work before you commit.