Simply Mortgages Logo
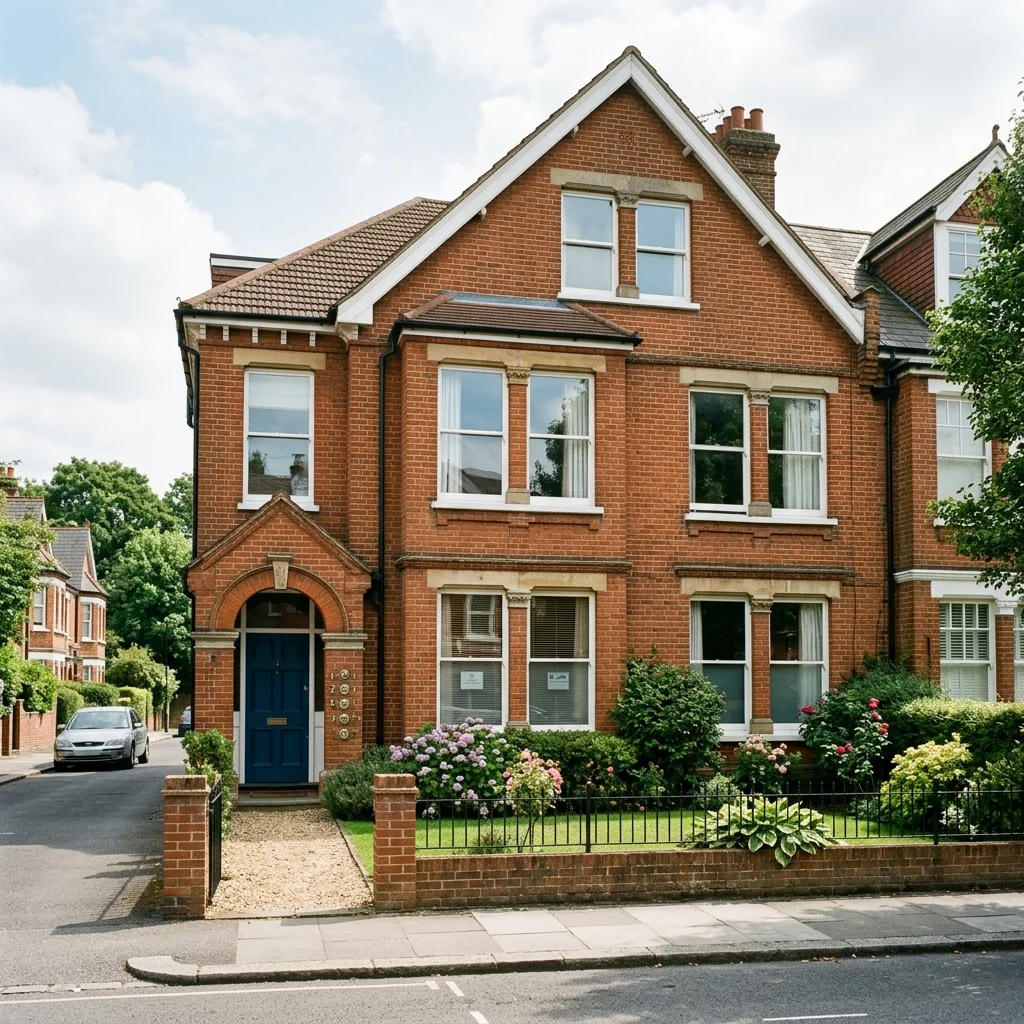
Large Victorian house converted to HMO

HMO Mortgages

Finance for multi-let properties

Houses in Multiple Occupation can generate higher gross yields than single lets, but costs and returns vary and specialist mortgage products may be needed. We work with lenders who understand HMO licensing, room-by-room rental calculations and the specific risks involved.

Talk to us

Mortgage advice, made simple

Get clear advice before you apply.

Tell us about the property, licence and rental plan.

  • FCA regulated, whole-of-market mortgage advice.
  • No jargon and no pressure to proceed.
  • We explain fees, risks and next steps before any application.

Your home may be repossessed if you do not keep up repayments on your mortgage. Some specialist or buy-to-let finance may not be regulated by the FCA.

Prefer to talk? Call 01772 217917.

FCA Regulated
Licensed & unlicensed
Higher yields
LTV subject to criteria

What counts as an HMO?

A House in Multiple Occupation is a property rented by three or more tenants who form two or more separate households and share facilities such as a kitchen or bathroom. In England, most HMOs occupied by five or more people from two or more households who share facilities require a mandatory licence. Rules differ elsewhere in the UK.

Many local authorities also run additional licensing schemes that capture smaller HMOs. We check the licensing position as part of our process and only approach lenders who are comfortable with the specific setup.

Types of HMO we finance

Small HMOs (3 to 6 rooms)

Shared houses with individual room lets. These are the most common HMO type and the widest range of lenders will consider them. Rates are close to standard buy to let.

Large HMOs (7+ rooms)

Larger properties with seven or more lettable rooms. Fewer lenders operate in this space, but rates can still be competitive. We have access to specialist funds that understand large HMO operations.

Conversions

Purchasing a standard house and converting it to an HMO. We can arrange bridging finance for the purchase and refurbishment, then refinance onto a long-term HMO mortgage once the work is complete and the licence is in place.

Rental calculations

HMO lenders assess rental income room by room. The assessed rent must meet the lender's stressed interest-cover test. HMO requirements can exceed 145%, depending on the lender and application. Higher combined rent does not guarantee affordability: HMO stress tests, costs and void periods still matter.

Yield advantage

HMO yields depend on the purchase price, achievable rent and occupancy. Compare both gross yield and income after costs. The trade-off is more hands-on management and stricter regulatory requirements. We match you with lenders who price for the yield, not just the risk.

Common questions

Do I need a licence?
In England, most HMOs with five or more occupants from two or more households sharing facilities require a mandatory licence. Smaller HMOs may need additional licensing. Rules differ elsewhere in the UK; check with the relevant council.
What deposit do I need?
Deposit requirements depend on the lender, property, rental assessment and landlord experience. We check available loan-to-value limits for your case.
Can I buy through a company?
Yes. HMO mortgages are available for both personal and limited company purchases. The same SPV structure and SIC code requirements apply as with standard Ltd Co BTL.
What about Article 4 areas?
Some local authorities have introduced Article 4 directions that require planning permission to convert a property to an HMO. Lenders will check this as part of their assessment. We make sure the planning position is clear before submitting an application.

Other investment services

Buy to Let

Standard buy to let mortgages for landlords.

Ltd Company BTL

Tax-efficient portfolio lending through a company.

Holiday Let

Finance for furnished holiday lettings.

Ready when you are

Ready to make the next move?

Send us a few details or call directly. We will help you work out the clearest route from here.

Send a message Call 01772 217917

Essential storage remembers your choice. Enquiry forms and calculators work without optional cookies.

Allow Google tracking tools and remember advertising click IDs and campaign details for up to 30 days.

Allow the Elfsight reviews widget and its review-view cookie. This is separate from advertising measurement.