Simply Mortgages Logo
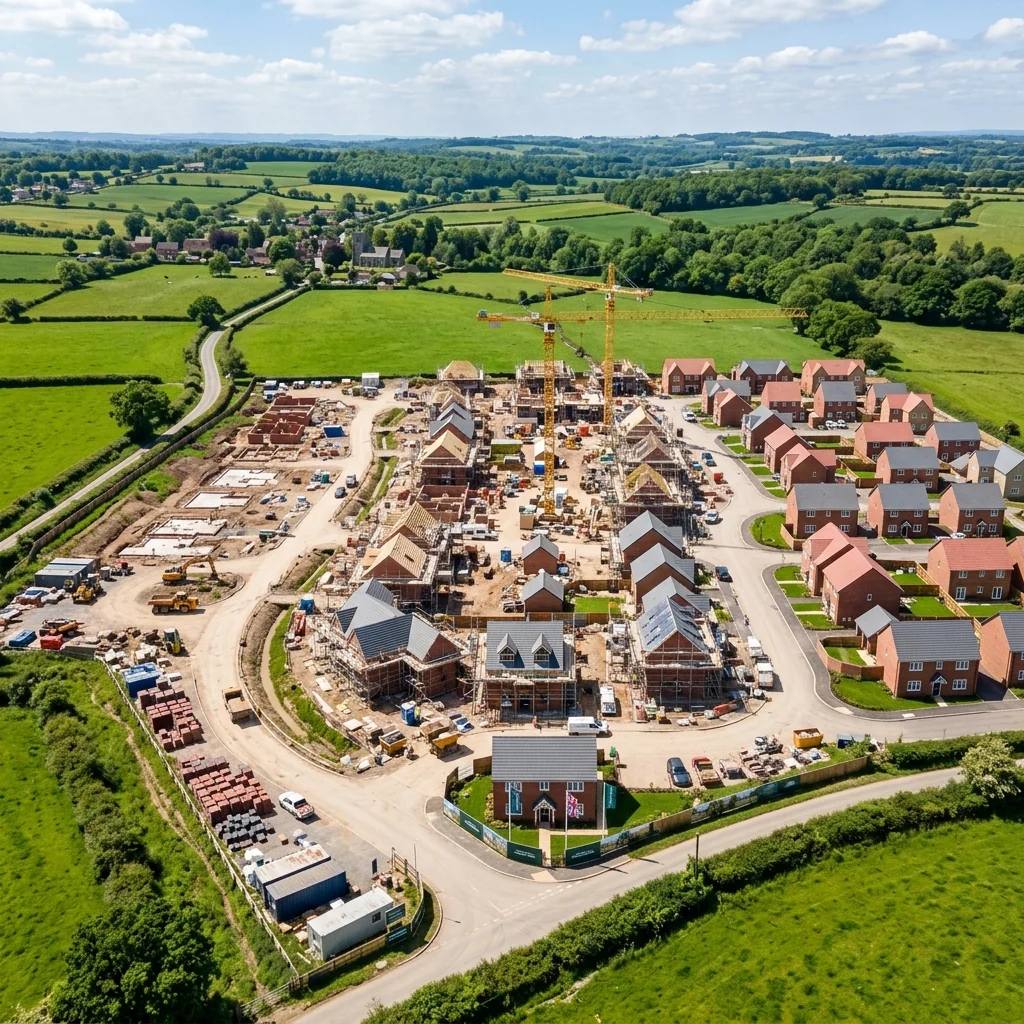
Aerial view of a UK housing development under construction

DEVELOPMENT FINANCE

Fund your next
development.

We arrange staged-drawdown finance for residential and commercial developers. From land acquisition through to build completion, we match your project to lenders who actually understand construction.

Discuss Your Project 01772 217917

Mortgage advice, made simple

Get clear advice before you apply.

Tell us about the site, build stage and exit route.

  • FCA regulated, whole-of-market mortgage advice.
  • No jargon and no pressure to proceed.
  • We explain fees, risks and next steps before any application.

Your home may be repossessed if you do not keep up repayments on your mortgage. Some specialist or buy-to-let finance may not be regulated by the FCA.

Prefer to talk? Call 01772 217917.

GDV-based lending limits
Phased Drawdowns
First-Time Developers
Rolled-Up Interest

How development finance works

Development loans can fund the land purchase and release further funds as construction progresses. Lending is limited by the lender's assessment of costs, completed value and your equity contribution.

Some facilities roll up interest rather than require monthly interest payments. The balance is due by the agreed repayment date; sale or refinancing must provide a viable exit.

What we arrange finance for

Residential

Single dwellings, multi-unit estates, apartment blocks, barn conversions and change-of-use projects.

Commercial

Retail units, office space, industrial premises, mixed-use schemes and student accommodation.

Lenders have very different appetites for residential versus commercial end-use. We know which funders suit which project type, and we present your scheme to the right underwriter first time.

Common questions

First-time developers
Most commercial lenders prefer a track record of completed projects, but we have access to specialist funders who will back first-time developers. The key is presenting a strong professional team: architects, project managers, quantity surveyors, and an experienced main contractor. A strong team supports the application, but funding still depends on the project and lender assessment.
Staged drawdowns explained
Your lender appoints a monitoring surveyor (QS) who inspects the site at each agreed milestone. Once they sign off, the next tranche of funding is released. This protects both you and the lender, and it means you only pay interest on money that has actually been drawn.
Planning permission requirements
Most lenders require full planning permission (FPP) before they will commit. Some will consider outline planning or permitted development rights, but the terms are generally stronger with FPP in place. We can advise on the best time to approach a lender based on where your planning application stands.
Exit strategies
Every development loan needs a clear exit. The two most common routes are selling the completed units on the open market, or refinancing onto individual buy-to-let mortgages if you plan to hold the stock. We stress-test your exit before we submit the application.

From the cost plan to the final sale

From full planning permission and Section 106 agreements to QS drawdowns and exit strategies, we handle the financial mechanics of your project so you can concentrate on delivering the build.
Ready when you are

Ready to make the next move?

Send us a few details or call directly. We will help you work out the clearest route from here.

Send a message Call 01772 217917

Essential storage remembers your choice. Enquiry forms and calculators work without optional cookies.

Allow Google tracking tools and remember advertising click IDs and campaign details for up to 30 days.

Allow the Elfsight reviews widget and its review-view cookie. This is separate from advertising measurement.